Malta residency and citizenship: Three key reforms for 2026–2027
by Kevin Mifsud
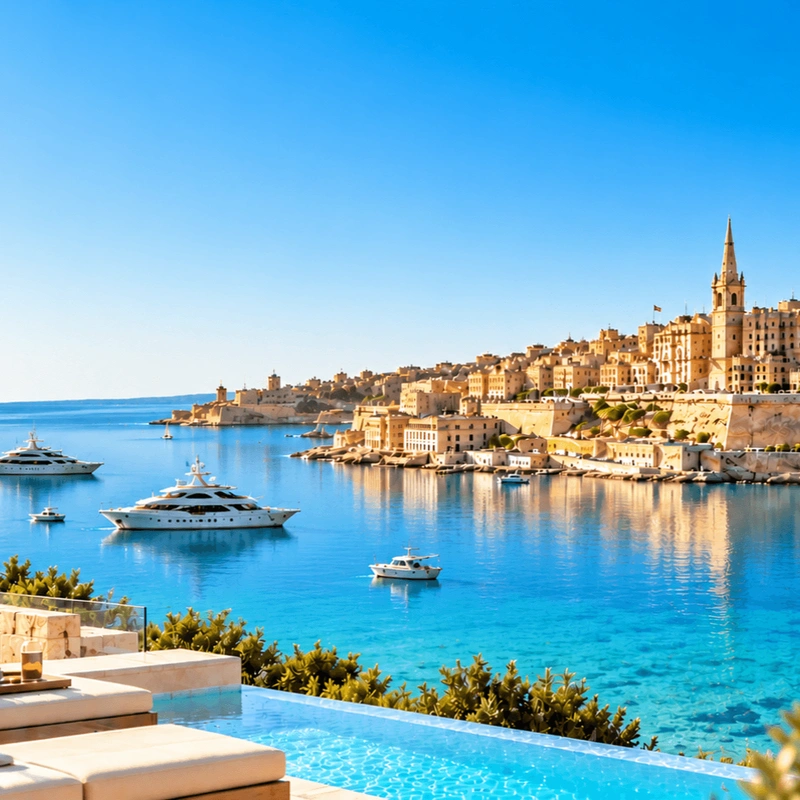
Malta continues to attract individuals and families seeking EU access, an established tax system, and a Mediterranean lifestyle. For those considering Malta as a base, three important reforms are reshaping the residence and citizenship landscape for 2026–2027.
Tax residence: a new consolidated programme
From 01 January 2027, Legal Notice 195 of 2026 brings Malta’s special tax residence schemes, including the Global Residence Programme (GRP) and The Residence Programme (TRP), under a new Individual Tax Programme.
Currently, TRP caters for European Union, European Economic Area (EEA), and Swiss nationals, while GRP generally applies to other nationals. Beneficiaries may enjoy a 15% tax rate on qualifying foreign income remitted to Malta, subject to a minimum annual tax of EUR 15,000.
The new programme retains the 15% rate but introduces higher minimum tax, property thresholds, and application fees, together with a five-year renewal cycle. Timing matters: applications submitted by 31 December 2026 may retain the current framework through 2031.
For US and Canadian citizens, Malta’s rules determine Maltese taxation only; home-country obligations remain subject to domestic rules and applicable tax treaties.
Citizenship: Legislative changes
Following the Court of Justice of the European Union’s judgment of 29 April 2025, Malta revised its citizenship framework in July 2025. The investment-linked route was repealed, and Citizenship by Merit under Article 10(9) of the Citizenship Act is now Malta’s sole legal basis to exceptional naturalisation, it is a discretionary grant reserved for individuals who demonstrate an exceptional contribution to Malta or humanity in fields such as science, philanthropy and economic development. The framework also requires a genuine footprint in Malta, including at least eight months of residence preceding the naturalisation application.
Permanent residence: greater flexibility
For non-EU nationals, the Malta Permanent Residence Programme (MPRP) remains an attractive route to permanent residence in Malta, with Schengen travel of up to 90 days in any 180-day period.
Following Legal Notice 146 of 2025, applicants may obtain a one-year temporary residence permit while their permanent residence application is processed.
The programme requires government contributions and fees, qualifying property through purchase or lease, and a philanthropic donation, with no minimum annual physical stay requirement.
Why timing matters
These three changes serve different objectives. The right solution depends on nationality, tax position, family circumstances, and long-term plans. With transitional provisions applying during 2026, timing can make a real difference. For those considering Malta, now is an ideal time to assess the available options and identify the route best suited to their objectives.
Kevin Mifsud is the CEO of KMFinco Audit & Assurance Ltd. A GGI member since 2004, Kevin advises international clients on audit, taxation, advisory, and business matters, bringing together technical expertise, commercial insight, and a pragmatic, solutions-driven approach.